The short answer: Medicare is health insurance, not long-term care insurance
Original Medicare (Parts A and B) was built to cover hospital stays, doctor visits, and short-term recovery care. It was never designed to pay for the ongoing help most seniors eventually need: assistance with bathing, dressing, meals, medication reminders, or supervision because of memory loss. That kind of help is called “custodial care,” and Medicare excludes it almost entirely.
This is one of the most common and expensive surprises families run into. If you’re researching care for a parent right now, it’s worth reading our full guide on how to find senior care for a parent alongside this article, since the two questions (what’s covered and where to actually find good care) go hand in hand.
What Medicare actually covers
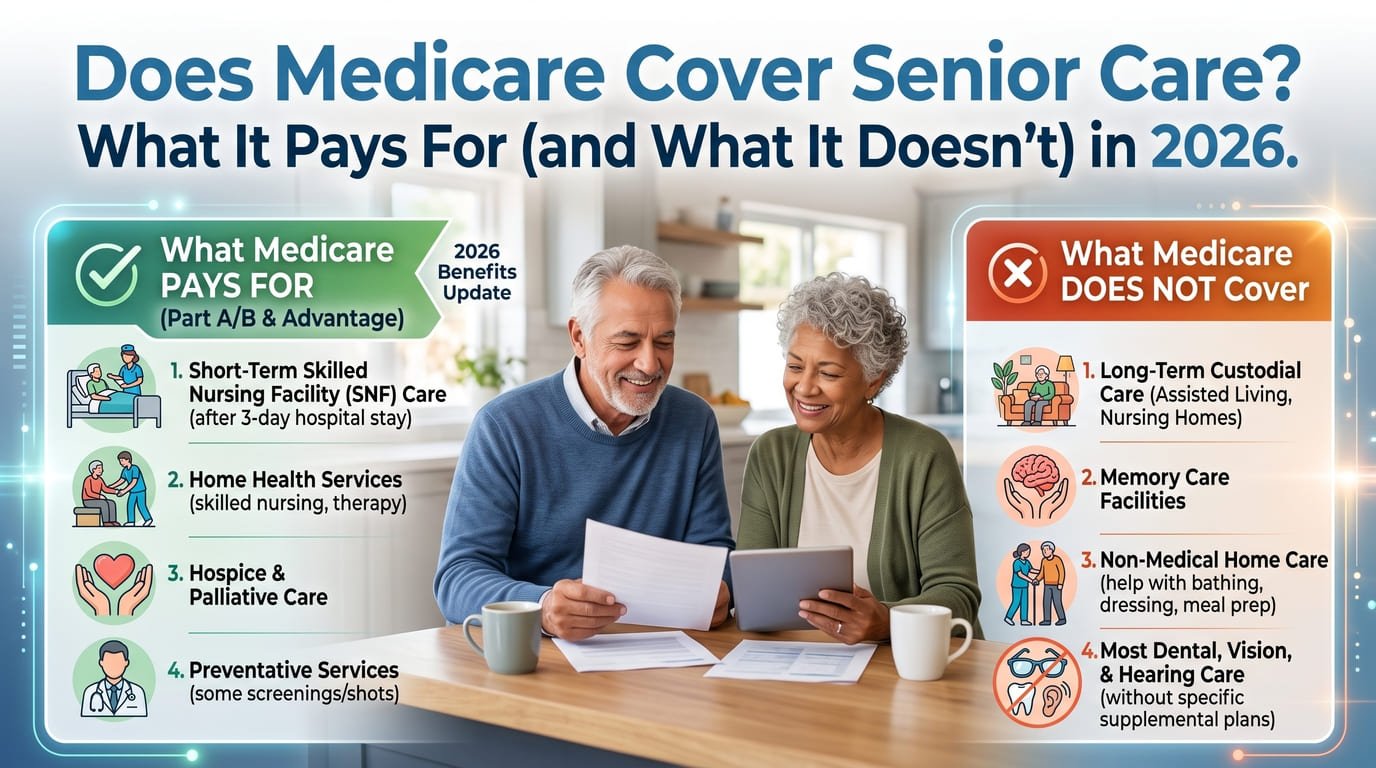
Medicare Part A and Part B do pay for some care that looks similar to senior care on the surface, but each has strict rules attached:
- Skilled home health care (Part A/B): part-time or intermittent skilled nursing, physical therapy, occupational therapy, or speech-language pathology, when ordered by a doctor and delivered by a Medicare-certified home health agency.
- Skilled nursing facility (SNF) care (Part A): up to 100 days per benefit period, but only after a qualifying 3-day inpatient hospital stay, and only for skilled rehab or nursing needs.
- Hospice care (Part A): comfort-focused care for a terminal diagnosis, including some home health aide support tied directly to the hospice plan of care.
- Doctor visits, medical equipment, and preventive services (Part B): wheelchairs, walkers, hospital beds, and routine screenings.
Notice the pattern: every category above is tied to a skilled medical need, ordered by a physician, and time-limited. None of it is designed to fund ongoing daily assistance.
What Medicare does not cover
This is the part that catches most families off guard:
- Custodial care of any kind (help with bathing, dressing, toileting, eating, or mobility) when it’s the only care needed
- Long-term stays in a nursing home once skilled care is no longer required
- Assisted living rent, room and board, or personal care services
- Adult day care programs (with narrow exceptions under some Medicare Advantage plans)
- 24-hour home care or live-in caregivers
- Homemaker services like cleaning, laundry, or meal preparation on their own
If a parent simply needs help getting dressed and managing meals, and has no skilled nursing or therapy need behind it, Medicare will not pay for that help, no matter how many hours a week it’s needed.
Medicare and home health aides
Medicare will sometimes cover a home health aide, but only as a secondary benefit attached to skilled care, and only under a specific set of rules. We cover this in full detail, including the homebound requirement and how many hours are typically approved, in our companion article: Does Medicare Cover Home Health Aides?
Medicare and skilled nursing facilities
For 2026, Medicare Part A covers a SNF stay as follows:
- Days 1–20: fully covered, $0 coinsurance, after a qualifying hospital stay
- Days 21–100: $217 per day coinsurance
- Day 101 and beyond: the beneficiary pays 100% of the cost
The catch is that the stay must be for skilled rehabilitation or nursing, not for ongoing custodial supervision. Once a patient plateaus and no longer needs daily skilled care, Medicare coverage typically ends, even if the family isn’t ready to bring them home.
Medicare and assisted living
Medicare does not pay for assisted living, period. It’s classified as a residential and personal care setting, not a medical one, so room, board, and day-to-day assistance are the resident’s responsibility. Some Medicare Advantage plans now offer limited supplemental benefits that touch personal care, but they don’t cover the cost of the facility itself.
Do Medicare Advantage plans cover more?
Since 2019, CMS rules have allowed Medicare Advantage (Part C) plans to offer limited “special supplemental benefits” for chronically ill members, which can include things like in-home personal care, meal delivery, or adult day care. Availability varies enormously by plan, county, and year, and these benefits are usually capped at a small number of hours or dollars annually. They supplement, and don’t replace, the cost of ongoing senior care.
Coverage at a glance
| Type of care | Original Medicare | Medicare Advantage |
|---|---|---|
| Short-term skilled home health | Covered if criteria met | Covered if criteria met |
| SNF rehab (up to 100 days) | Covered with coinsurance after day 20 | Covered, terms vary by plan |
| Long-term custodial home care | Not covered | Not covered; limited supplemental benefits in some plans |
| Assisted living room and board | Not covered | Not covered |
| Long-term nursing home stay | Not covered | Not covered |
How families pay for the gap
Since Medicare doesn’t fund ongoing senior care, families typically rely on one or more of the following: paying out of pocket, long-term care insurance purchased in advance, Medicaid once assets and income qualify, VA Aid and Attendance for eligible veterans, or a mix of family caregiving and part-time paid help. We break each path down, including how Medicaid’s rules differ from Medicare’s, in Medicare vs. Medicaid for Senior Care and How to Pay for Senior Care When Medicare Falls Short.
If you’re at the stage of actually comparing care options for a parent, the practical next step is our guide to how to find senior care for a parent, which walks through evaluating in-home care, assisted living, and memory care once you know what you’re paying for yourself.
Frequently asked questions
Does Medicare pay for a caregiver to come to the house?
Only in a narrow set of circumstances tied to skilled home health care, and only for a limited number of hours per week alongside skilled nursing or therapy. It does not pay for a caregiver whose only job is help with daily activities.
Will Medicare pay for a nursing home if my parent can’t go home?
Medicare covers a nursing home stay only while skilled rehabilitation or nursing care is medically necessary, up to 100 days per benefit period. It does not pay for a long-term nursing home stay once that skilled need ends, regardless of whether the family is ready to bring the person home.
Is Medicaid the same as Medicare for senior care?
No. Medicare is federal health insurance available regardless of income, and it excludes most long-term care. Medicaid is a joint federal-state program based on financial need, and it’s the primary public payer for long-term custodial care in the U.S. See our full comparison: Medicare vs. Medicaid for Senior Care.
Does Medicare cover home health aides for dementia care?
Medicare may cover a home health aide alongside skilled nursing or therapy visits for someone with dementia, but it does not cover full-time supervision or custodial dementia care on its own.